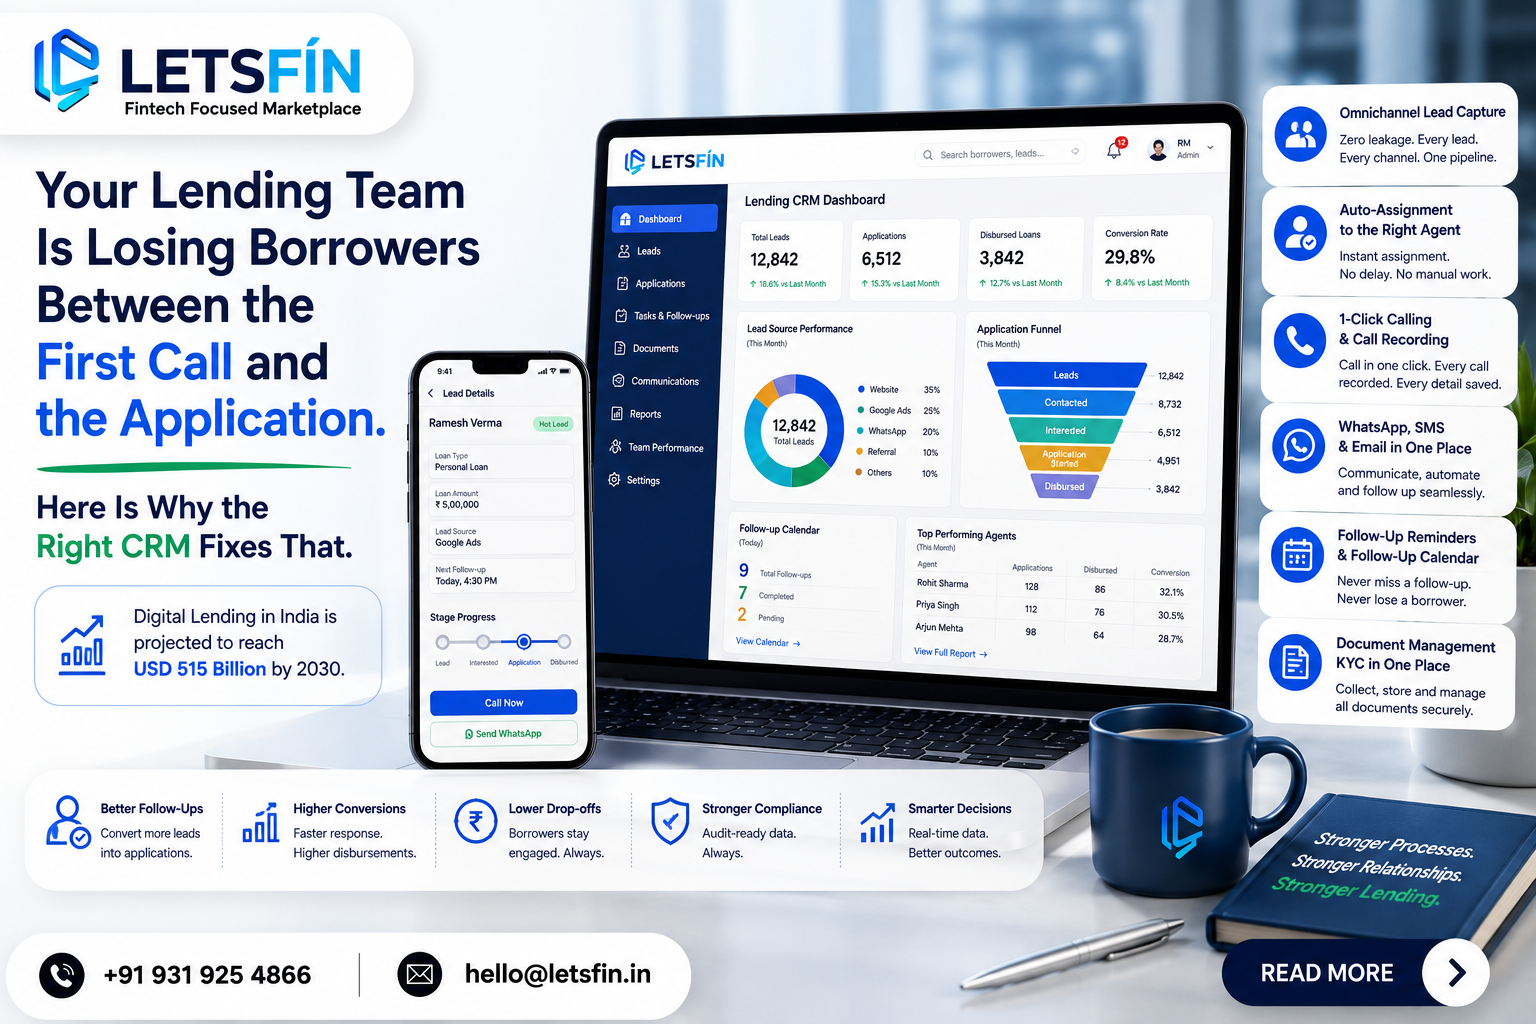
Your Lending Team Is Losing Borrowers Between the First Call and the Application. Here Is Why the Right CRM Fixes That.
August 21, 2026
A borrower enquires about a personal loan on Monday. The sales agent logs the call. Tuesday passes. Wednesday, a different agent calls back with no context of Monday's conversation. The borrower has already applied elsewhere. This is not a rare scenario. It is what happens every week inside NBFCs and fintech lending platforms that are running their borrower relationships on tools that were not built for the complexity of a loan product.
The Indian digital lending market is projected to reach USD 515 billion by 2030. The lenders capturing that growth are not doing anything exotic — they are simply closing the workflow gaps their competitors have accepted as normal. The right CRM infrastructure is how they are doing it.
What a CRM Built for Lending Actually Does
A loan is not a sales deal. It has stages that a generic tool cannot handle — lead qualification, document collection, follow-up sequences, team handovers, and a borrower communication cadence that runs from first enquiry through to disbursement. Each stage has different owners, different data requirements, and different timelines. When these stages are managed on spreadsheets or a generic CRM, you get the same failures every time.
- Lead leakage across channels: Leads from your website, WhatsApp, social media, Google Ads, and referral partners sit in different places with no unified view. High-intent borrowers fall through because nobody owns the follow-up. The right CRM automatically captures leads from all these channels into one pipeline — with zero manual effort and zero leakage.
- No context continuity across your team: When a borrower calls back and gets a different agent, that agent has no idea what was discussed before. Every previous conversation, document shared, and stage update should be visible to every team member in one place — so the borrower never has to repeat themselves.
- Follow-ups missed because they live in people's heads: Missed follow-ups are missed loans. A CRM with automated follow-up reminders and a centralised follow-up calendar ensures every borrower gets contacted at the right time — regardless of which agent is on that day.
- No visibility into team performance: Which agent is closing the most applications? Which lead source is converting best? Without real-time performance reports and hour-by-hour activity tracking, managers are making decisions on guesswork.
- Document collection is a manual chase: KYC documents, income proof, bank statements — chasing these over WhatsApp threads and email is slow and error-prone. A CRM with document management stores all borrower documents in one place, accessible to every team member who needs them.
The borrower who dropped off between stage two and stage three of your process did not leave because your product was wrong. They left because your follow-up was three days late and your competitor's was same-day. That is a CRM problem, not a product problem.
The Features That Actually Move the Numbers for Lenders
Here is what the right CRM infrastructure delivers across the lending workflow — based on features verified to exist in the platforms Letsfin provides access to.
Omnichannel Lead Capture — Zero Leakage: Leads captured automatically from your website, Google Ads, Facebook, WhatsApp, IVR calls, and chatbots — all flowing into one centralised pipeline. No manual entry. No duplicate records. Uniqueness rules eliminate lead duplication automatically. Every enquiry is accounted for from the moment it arrives.
Auto-Assignment to the Right Agent: Leads are automatically assigned to the right sales person based on availability, location, loan product type, or any other criteria you define. Senior agents get high-intent leads instantly. No manual distribution. No delay between lead arrival and first contact.
1-Click Calling and Call Recording: Agents call borrowers with a single click — no manual dialling, no wasted time, no misdials. Every call is automatically recorded and logged against the borrower record. Managers can review recordings to train agents, identify what is working, and ensure quality across every conversation.
Follow-Up Reminders and Follow-Up Calendar: Automated reminders ensure no follow-up is ever missed. Agents receive WhatsApp notifications when it is time to call. Managers get a full calendar view of every follow-up scheduled across the team — daily, weekly, monthly — with missed follow-ups flagged automatically.
WhatsApp, SMS, and Email from One Place: Send borrower communications — welcome messages, document requests, application status updates, EMI reminders — directly from the CRM via WhatsApp, SMS, or email. Bulk messaging to segmented borrower lists. Automated messages triggered by stage changes. No switching between apps.
Document Management — KYC in One Place: All borrower documents — PAN, Aadhaar, income proof, bank statements — collected and stored in the CRM against the borrower record. No digging through WhatsApp chats. No requesting the same document twice. Every team member who needs access to a document has it, instantly.
Custom Pipelines for Every Product and Team: Create separate pipelines for personal loans, business loans, home loans, and any other product your team sells. Configure pipeline stages to match your exact origination workflow. Pre-sales, sales, credit, and operations can each have their own view of the same borrower journey.
Workflow Automation — Zero Manual Tasks: Automate repetitive tasks that currently consume your team's time — sending welcome messages to new leads, assigning leads based on predefined rules, scheduling follow-up reminders, sending document collection requests, triggering stage-change notifications. Every step that does not require a human decision gets automated.
Custom Fields for Lending-Specific Data: Capture CIBIL score, loan amount, tenure preference, employment type, income, KYC status, and any other data point your credit team needs — in custom fields built into the borrower record. Filter and segment your pipeline by any of these fields to identify the most qualified prospects for immediate follow-up.
Real-Time Performance Reports and Dashboards: Track every metric that matters — leads by source, conversion rate by stage, agent performance, calls made, deals closed, revenue forecasts. Customisable dashboards that give managers a complete picture of the lending pipeline in real time. Reports accessible from mobile, not just desktop.
Role-Based Access Control: Define exactly which team members can see which borrower data. Sensitive financial information visible only to authorised users. Field-level access controls ensure your data remains secure even as your team scales to hundreds of agents across multiple locations.
Mobile CRM — Full Access on the Go: The complete CRM — lead pipeline, borrower records, call logs, follow-up calendar, documents, reports — accessible from a mobile app. Field sales agents and DSAs can manage their pipelines and log interactions from anywhere, without being tied to a desktop.
Payment Reminders and Integration: Send automated payment reminders and links directly to borrowers from within the CRM. Track payment status against borrower records. For lending teams managing EMI collection at the CRM layer, this closes the loop between the sales relationship and the repayment relationship.
Why This Matters Specifically for NBFCs and Fintech Lenders
The lending workflow has specific characteristics that make CRM infrastructure more critical — and more complex — than in most other businesses.
- High lead volumes with thin margins per conversion: A personal loan team handling 500 leads a day cannot afford manual follow-up processes. Every missed follow-up and every lead that falls through the cracks is revenue that does not come back.
- Multi-stage process with multiple owners: The borrower journey from enquiry to disbursement involves sales, credit, operations, and collections — often different teams with different systems. A CRM that gives every team a unified view of the same borrower eliminates the handover gaps where applications stall.
- Compliance requirement for documented interactions: Every borrower communication, every document collected, every stage change needs to be logged and retrievable. A CRM with automatic call recording, interaction history, and document storage provides this audit trail without any additional effort from the team.
- Repeat borrowers are the highest-value segment: A borrower who repaid their first loan on time is your best prospect for a second loan. A CRM that tracks the full borrower history and flags repeat loan eligibility at the right moment turns your existing book into a growth channel.
The lenders growing fastest right now are not the ones with the best products. They are the ones with the tightest follow-up processes, the lowest lead leakage, and the clearest visibility into their pipeline. That is what the right CRM delivers.
How Letsfin Brings This to Your Lending Operation
Letsfin provides CRM infrastructure specifically configured for NBFCs, digital lenders, and fintech platforms — with the lead management, calling, document collection, automation, and reporting features that the lending workflow requires.
- One pipeline for every loan product and team: Personal loans, business loans, microfinance, DSA networks — each managed in a separate, customised pipeline with stages that match your actual origination process.
- Automatic lead capture from every channel: Website, WhatsApp, Google Ads, Facebook, IVR, chatbots — all feeding into one CRM with zero manual entry and zero duplication.
- 1-click calling with automatic recording and logging: Every agent call one click away. Every conversation recorded, logged, and attached to the borrower record automatically.
- WhatsApp automation for borrower communication: Welcome messages, document requests, follow-up nudges, payment reminders — automated and sent directly from the CRM at the right stage of the borrower journey.
- KYC document collection and storage: All borrower documents collected and stored in one place, linked to the borrower record, accessible to every authorised team member.
- Real-time dashboards for managers: Lead source performance, agent conversion rates, pipeline health, revenue forecasts — visible in real time, accessible on mobile, actionable without waiting for a Monday morning report.
The Bottom Line
India's lending market is growing at 30 percent annually. The lead volumes, the borrower expectations, and the competition are all increasing together. The lenders who will capture disproportionate share of that growth are not going to do it by hiring more agents. They are going to do it by making every agent they have significantly more effective — with a CRM that ensures no lead leaks, no follow-up is missed, every borrower has a complete record, and every manager has full visibility into what is happening across the team.
If your current setup is not delivering that, reach out to the Letsfin team. The right CRM infrastructure for your lending operation is ready to deploy.